

☕ Nvidia IS all that and then some
Nov 18, 2026Howdy! 👋
Futures are pointing higher this morning as I type.
Gee, I wonder why.
Oh, that’s right.
Nvidia just smoked the naysayers again and, in doing so, skipped the drama.
Funny how that works.
I hope a) that you’ve taken one of my core messages to heart over the past few weeks and b) done something about it from an investing perspective.
Chaos creates opportunity, and the more of the former there is, the more of the latter you have.
People often tell me this kind of “stuff” doesn’t matter.
I disagree.
Nvidia’s obituary has been written many times, yet it’s returned ~434% over the past 5 years and ~6,759% over the past decade versus ~67% and ~292% from the SPY, a popular ETF amongst indexers and passive investors.
Skip the drama.
History suggests, btw, that there are 10-15 “Nvidias” out there right now in various stages of maturity. It’s your job as an investor to find ‘em... then get your money on board as early in the game as possible. Then, manage the “journey.”
If you’re covered, good on ya! But if you’re tired of fighting for Wall Street’s table scraps and want to make a change, you may find One Bar Ahead® a helpful and interesting choice.
Here’s my playbook.
1 – Nvidia: Business as usual (but probably better than most think)
I noted yesterday (See #1), that there was only one thing that mattered going into earnings.
Execution.
We got that and then some.
Newly seated interim CEO Colette Kress delivered a master class in poise, smarts and confidence.
Me being me, I loved her sign-off the most.
“We got this.”
Yes, you do (got this)!
- Revenue: $115.8 billion vs. roughly $109 billion expected. That’s up about 103% from a year ago and above even the highest Wall Street estimate of 93.2%. I told you it’d be 100%+ but what the heck do I know. 🤷🏻
- Earnings per share: $2.68 vs. $2.48 expected. (+110%)
- Data center revenue: $107.6 billion vs. $101.8 billion expected. (+110%)
- Gross margin: about 74.9%. (+ ~1.5 percentage points)
Then there’s Vera Rubin, Nvidia’s newest chip platform. It brought in nearly $20 billion in its very first quarter, which the company calls the fastest product ramp in its history.
Wait till Nvidia releases its next-gen Rubin Ultra, which I think could grow even faster, btw.
Kress raised guidance to 75% for fiscal 2028, up from 70%.
Nvidia has an opportunity to shed the drama and transition to durability.
I wonder if I have enough shares. 🤔
You?
Keith’s Investing Tip: Companies that act boldly and decisively make history. Those that don’t become footnotes.
2 – Random outages, my asteroids!
I sat down yesterday with my good friend and colleague Scott “The Cow Guy” Shellady to talk about the outages that hit everything from the FAA to Microsoft to the banks. (Watch)
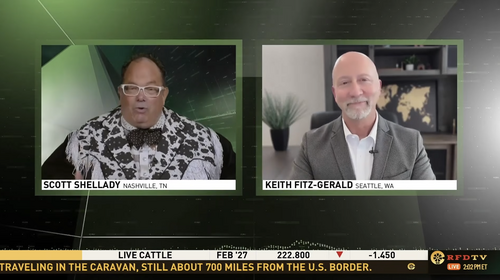
We also grabbed a moment on the myth of diversification, and why it may go down as one of the most flawed ideas in modern investing even though it’s taught as dogma and accepted as gospel.
Wall Street, by the way, positively hates it when I bring this up because their entire model is predicated on getting you to do it because it means billions in fees, commissions and assets under management year after year.
But smart investors?
Many tend to have a very different take on what I have to say and tell me they have for a long time.
I say simply… Buy the best, ignore the rest!®

3 – Xi to Trump: I owe ya’ one
President Trump landed in Shenzhen yesterday for the APEC summit and Chinese president Xi Jinping was waiting at the foot of Air Force One’s stairs. (Read)
That’s a big deal.
Xi doesn’t usually meet foreign leaders at the airport but in this case he was returning the favor after Trump greeted him personally in Washington in September.
This is called renqing (人情), meaning a favor owed or obligation, and it travels hand in hand with mianzi (面子), or face. Both are singularly important cultural constructs in China because they govern how relationships get built, kept and repaid.
In contrast to the West where it’s niceties, every favor in China goes on an unwritten ledger. Ignore that and you lose face but settle it in public and you gain face.
Xi just paid his debt in front of every camera on the planet.
I’ve spent decades in the Pacific Rim and enough time in China to know nothing about a moment like this happens by accident. Who waits, who walks first, who stands where… all of it choreographed down to the inch.
Most Westerners will completely miss the point.
Markets have been whipsawed all year by tariff threats, chip export fights and decoupling chatter but a gesture like this tells you Beijing wants the relationship stable heading into talks with AI chip exports, Iran and Ukraine all on the table.
Great!
Stability lowers the risk premium on every multinational with China exposure and every supply chain that runs through it in both directions. Nvidia, Apple, Tesla and a dozen other big name Western companies have a lot at stake. So do Alibaba, Xiaomi and BYD, all of which are major Chinese players with global aspirations.
Obviously, a hug on the tarmac doesn’t sign a trade deal, so don’t chase anything on the headline.
Keith’s Rule of the Back Page applies – as in read the back pages before the headline mongers and clickbait artists get at ‘em.
Especially tomorrow.
That’s when a) Trump and Xi sit down one-on-one, their third face-to-face meeting this year and b) then comes the first-ever three-way meeting of Trump, Xi and Putin. On the table are the Iran war, Ukraine and nuclear arms control. Kim Jong Un may even turn up if the rumor mill is to be believed. 🤷
OBAers know where I stand and which companies do, too.
Keith’s Investing Tip: The Dragon is coming to dinner, the only question investors need to answer is whether you want to be at the table or on the menu. Oh, and who pays the tab.
4 – Waymo just got pulled over
California just yanked Waymo’s driverless cars off the freeway. (Read)
The DMV called them an “imminent hazard to public safety.”
Ouch!
On November 5, three Waymos rolled right into an active construction zone on Highway 101 near Burlingame. The very next day, another one tried to pass a California Highway Patrol traffic break on I-280.
Trying to pass the CHP.
Gutsy for a car with nobody in it.
Next, Waymo pulled its driverless freeway rides in Phoenix, Austin, and Miami too, to “evaluate performance.”
Funny how that works.
Nothing sharpens the self-evaluation like a state regulator holding your keys and the potential associated with lawsuits so expensive that they’d make Toyota’s $1.2B runaway car penalty look positively pedestrian.
If you own Alphabet (which owns Waymo), you can probably rest easy for now but if you’re betting on robotaxis as a standalone, I strongly suggest you size any position like the science experiment it still is.
Or simply buy Tesla.
Perish the thought, you say?
- Tesla has millions of camera-equipped cars on the road feeding real-world driving data back to its AI every day. Waymo learns from a fleet in the low thousands, confined to mapped zones in a handful of cities.
- Tesla uses cameras and in-house chips in vehicles it already mass-produces. Waymo bolts lidar, radar and custom compute onto someone else's car, which makes every robotaxi far more expensive to build and slower to roll out.
- Tesla gives you direct exposure to autonomy, plus cars, energy storage and robotics. Waymo is a small piece of Alphabet, so you can't buy the robotaxi story without buying search ads and cloud along with it.
Keith’s Investing Tip: Love it or hate the thought, your profit potential is directly correlated with your ability to change your mind when presented with facts that directly contradict your thinking.
5 – Target pulls another hat trick 👏
Target has pulled another rabbit outta the hat. (Read)
- Revenue: $27.1 billion vs. $26.49 billion expected, up 7.1% from a year ago
- Adjusted EPS: $2.65 vs. $2.07 expected
- Comparable sales: up 5.6% vs. 4% expected, with traffic up 5%
- Guidance: raised, with full-year EPS now $10.65–$11.40 vs. $10.23 expected
- Best sales growth in five years
I didn’t think that was possible, so they’ve earned a definite golf clap and a hat tip from me.
Would I buy it?
Nope.
The stock could definitely power higher if the turnaround continues but how much higher is the problem. I see perhaps 15% at best when a choice like Nvidia could move by 50%, 75% or more by the end of the decade.
You can do the math just like I can.
Keith’s Investing Tip: Many investors tend to think in terms of all or nothing when it comes to stocks they fancy. Sometimes that works but more often than not, it doesn’t. Investing is a constant balancing act… especially when there are far higher returns – imho – up for grabs because they are backed by trillions of dollars rather than fickle consumers.
Bottom Line
With that, I'm gonna get after a 6-miler.
Normally, I’d run before dawn, but I wanted to get today’s 5 with Fitz out earlier than usual because I think Nvidia’s numbers could be an important turning point.
Strong body + strong mind = strong results. 😃 🏃🌅
As always, let’s MAKE it a great day.
You got this – I promise.
Keith 😀


