

☕ The beginning of the end of Google as we know it or?
Oct 29, 2026Howdy! 👋
The markets are down this morning after Microsoft nailed it and Alphabet/Google biffed it.
To a point I have made many times over…
NOT all tech is the same.
Buy the best, ignore the rest!®… especially when it comes to some of the really big names that people regard as “safe” or too good to pass up.
Here’s my playbook.
1 – Buy this, not that
On Monday morning, Stuart Varney asked me which big tech report I was watching closest.
Microsoft.
Here’s exactly what I told him: “I expect them to come out not only well, but probably exceptionally well.” (Watch)
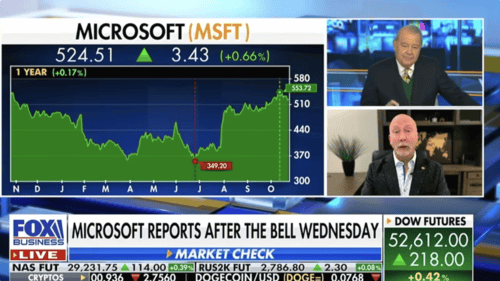
Last night, Team Nadella delivered.
Revenue hit $92.3 billion, up 19%. Microsoft Cloud brought in $63.9 billion, up 30%. That’s the part of the business that rents computing power and AI tools to other companies. (Read)
The real star was Azure, Microsoft’s cloud platform. It grew 48%, surpassing Microsoft’s own forecast of 44–45%.
Then there’s the “$50 billion capex test” I talked about on air.
Wall Street has been worried that Microsoft is spending a fortune on AI with nothing to show for it. I’m not. Capex came in at $45.2 billion while revenue continues to accelerate.
In other words, Microsoft has a bunch of viable businesses.
Shares rose sharply after hours but have since given that back in conjunction with the broader selloff – which is to be expected considering that more than 8,000 funds and institutions own Microsoft as do 1,600+ ETFs and it’s a heavyweight in virtually every major benchmark, including the S&P 500, the Nasdaq-100 and the Dow.
Then there’s Alphabet…
2 – The beginning of the end of Google as we know it?
I didn’t mince words ahead of the earnings report.
What’d I say?
Simply that, “I think that business [Google/Alphabet] has big problems.” (Watch)
And specifically, that “search is being disintermediated” – meaning that AI is cutting out the middleman. You ask a chatbot, you get your answer, and you never see a page of paid links.
Alphabet’s proponents wasted no time jumping all over me.
Too bad they had to be so nasty.
Last night, Alphabet missed on both revenue and earnings for the first time in nearly four years. (Read)
Why?
Three guesses and two don’t count.
Shares are down nearly 13% as I type.
To be fair, Google Cloud more than doubled, up 103% to $30.7 billion and that’s pretty good. But again, this is the part that most investors simply cannot grasp, let alone believe.
Google’s core business model is eating itself… customers and advertisers now have plenty of alternatives that don’t involve paying Alphabet/Google a single penny.
I think the problem gets a whole lot worse and that this may be the beginning of the end of Google as we know it.
Could I be wrong?
Absolutely… comes with the territory in this business which is why I’ll focus on being profitable and investing in other companies that I believe have none of the drama, a fraction of the risk and gobs more profit potential.
You can join me if you like or continue to fight for Wall Street’s table scraps.
It’s always your choice. 😀
3 – What to do about the Fed’s latest missive
The Fed left its key rate at 3.75–4% yesterday. (Read)
No surprise.
The vote was 10–2, and the two dissenters, Lisa Cook and Beth Hammack, both of whom wanted to raise rates. That comes on top of September’s quarter-point hike, the Fed’s first increase since 2023 and a BIG mistake to my way of thinking.
They still don’t get it, not that that’s unusual for policy wonks.
Rates are not the right tool.
Economic growth on its own does not cause inflation which makes rates a totally inappropriate response to a healthy, expanding economy. What’s more, if major banks do not adjust or tighten their actual lending standards in response to whatever shenanigans Team Fed comes up with, the Fed’s moves lose their effectiveness as an economic “steering wheel” for lack of a better term.
I say enough.
Meanwhile, I see so many investors wasting a lot of mental energy and a tremendous amount of profit potential worrying about what the Fed will or won’t do.
What I want you to understand – and I really need you to hear me on this – is that the Fed has never created value.
Businesses, innovation, and plenty of smart people do… so quit obsessing over the “smartest people in the room” and focus on those who are actually tasked with turning a buck.
Like the handful of world-class CEOs who are doing just that for investors.

4 – Great quarter, Merck. Now about 2028
Merck (MRK) is a popular stock (that I don’t own) for a variety of reasons.
The company just turned in some spectacular results:
- Adjusted earnings of $2.49 a share, a whopping $0.40 ahead of what Wall Street expected
- Revenue of $18.09 billion, up 5% from a year ago and $760 million above estimates
- Keytruda sales of $8.6 billion against the $7.73 billion analysts were looking for, including a record $830 million from Keytruda Qlex, the newer injectable version
- Winrevair, Merck’s lung disease drug, up 93% to $694 million
- Full-year sales guidance raised to $66.8 to $67.3 billion
Should you buy it?
I could make the argument that’d be a smart decision, but I fear that the folks cheering loudest this morning stopped reading at the headline.
Here’s why.
Roughly half of Merck’s revenue comes from one drug. Keytruda’s key U.S. patents start expiring in 2028, and the biosimilar crowd is already lined up at the door. Qlex is Merck’s attempt to move patients onto a newer, patent-protected version before the cliff arrives. Smart… but whether it works fast enough is another matter entirely.
Then there’s the fine print.
About $550 million of this quarter’s sales came from customers buying ahead of schedule, and Merck said so itself. In other words, that’s demand borrowed from future quarters.
Hmmm. 🧐
What concerns me most, though, is that profits actually fell. GAAP earnings slipped to $2.04 a share from $2.32 a year ago, while gross margin dropped from 77.7% to 72.9% as acquisition and restructuring costs piled up.
Merck is racing the calendar and spending billions in an effort to do that because they want to replace Keytruda revenue before the patents roll off.
My point is that a beat today doesn’t tell you who wins that race.
If you own MRK, there’s no reason to panic. If you don’t, I wouldn’t chase it on a headline pop. I want to see Qlex conversion and new launches carrying real weight first. If you want in anyway, a LowBall Order well below today’s price lets the market come to you.
Meanwhile and if you’re an OBAer, I suggest you stick with the plan. I think comparable offerings in the OBA Model Portfolio have considerably better upside potential and dividends which are important to income-oriented folks.
Keith’s Investing Tip: Price and value are different.
5 – When losers team up
DoorDash just agreed to buy Instacart for about $17 billion. That’s $65 a share, a 26% premium to where Instacart closed on October 22, before word of the talks leaked. (Read)
Here’s the kicker.
Back in 2021, these same two companies talked about a deal worth $40 to $50 billion – and I told you to avoid both.
Five years later, Instacart sells for roughly a third of that.
Hmmm.
Grocery delivery was supposed to be the pandemic gold mine. Then Walmart showed up and grabbed more than 30% of the online grocery market, Amazon kept doing what Amazon does, and Instacart’s stock went nowhere for two years.
Even Uber kicked the tires and walked away.
So now the company that brings you cold fries wants to marry the one bringing you bruised bananas, and Wall Street is calling it synergy. 🙄
Both companies are on borrowed time, imho.
Bottom Line
Markets reward knowledge, not guesswork.
You got this — I promise. 💯
As always, let’s MAKE it a great day!
Keith 😀


