

☕ Wall Street says JPMorgan "missed" - I say look again!
Oct 13, 2026Howdy! 👋
Red day across the board on new Iran warnings, bank earnings, higher oil and a chip “washout” that’s being attributed to a formerly almost unknown Chinese memory maker named ChangXin Memory Technologies, which said it’s made significant progress packing more data into smaller chips.
Or at least that’s the official headline version.
What’s really driving things is the same realization that we’ve talked about many times over the years… China is capable of scaling any product it makes faster and at a fraction of the cost when compared to Western makers.
Notably, Elon Musk agrees with me, observing that “When China figures out how to manufacture a product, their ability to scale is often greater than the rest of the world combined” – and that’s what traders have picked up on.
This doesn’t change the game longer term, so DO NOT GET FLUSTERED into doing something stupid like letting your emotions get the better of you and selling in a panic.
Instead, take a hard look at which names are getting put on sale for reasons that have nothing to do with their underlying business models… and buy if you can.
Short term fear always makes long term opportunity cheaper.
Here’s my playbook.
1 – Wall Street says JPMorgan “missed” – I say look again
Team Dimon reported Q3 earnings this morning, and the headlines are exactly what you’d expect despite a great quarter.
JPM “missed”… according to the bunch of analysts who don’t work for the company, aren’t privy to the C-Suite and who probably have never worked in banking itself. (Read) 🤷
Sigh.
I wish the analyst community would own up but, then again, I hear the tooth fairy still exists, too. So I’m not holding my breath.
To be fair, there are some super smart analysts out there, but they’re rarer than hen's teeth. The point I want you to take into consideration this morning is that investors risk doing themselves a serious disservice if they rely on what those folks have to say.
JPM is not a company in trouble:
- Net income: $15.3 billion, up 6% from a year ago
- Earnings per share: $5.57, up 10% year over year
- Revenue: $50.9 billion on a managed basis, up 8%
- Net interest income: $27 billion, up 13%
- Equity markets revenue: $5.0 billion, up a whopping 49%
- Investment banking fees: up 14% year over year
- Provision for credit losses: down 19%, which is bank-speak for “our borrowers are paying us back”
- CET1 capital ratio: 13.9%, meaning the fortress balance sheet is still very much a fortress
So where’s the “miss”?
FactSet’s consensus called for $5.93 a share. JPM reported $5.57. But buried in there is a $658 million one-time loss on investment securities that knocked $0.18 off EPS. Strip it out and the bank earned $5.75 a share.
Hmmm.
“Consensus” itself was all over the map heading into today’s earnings… anywhere from $5.82 to $5.93 depending on which survey you read. My experience is that it’s hard to miss a target when the gang involved in setting it continue to move it all over the map. 🙄
The sooner you understand what I am about to say, the better off your portfolio will be.
Headlines are written for clicks, but earnings releases are written for investors.
Big difference.
In plain English… JPMorgan grew profits, grew revenue, grew lending income, set aside less money for bad loans, and kept more capital than most banks on the planet. Notably, Dimon also trimmed buybacks to $664 million this quarter because the bank sees attractive returns deploying that capital elsewhere; a call that management wouldn’t make if it were worried about the business.
- If you own JPM, I strongly suggest you stand firm if at all possible.
- If you don’t and you’ve been waiting for a pullback, a “miss” headline on a quarter like this one is the sort of gift Wall Street hands out more often than most folks realize.
- LowBall Orders, btw, were built for exactly this kind of overreaction. If you’re a member of the OBA Family, check yesterday’s email update for the specific levels I shared with you ahead of earnings for this scenario. 😃
Keith’s Investing Tip: Always read the earnings release before you read the headlines about it, because I can almost guarantee you that analysts certainly didn’t.
2 – UnitedHealth makes it three for three
The hat trick continues – and I’m thrilled because I didn’t think that the company would be able to pull this off.
I’m super happy to see what’s happening.
UnitedHealth Group, you see, reported this morning and, for the 3rd quarter running, the numbers were good. (Read)
- Adjusted EPS came in at $4.69 vs. $4.14 expected, +61% YoY
- Revenue hit $112.69 billion vs. about $111.4 billion expected, –0.4% YoY
- Medical cost ratio: 88.4%, better than expected and down 1.5 points from 89.9% a year ago. That’s the share of premiums spent on patient care, so lower means a more profitable insurer.
- Full-year earnings outlook raised to at least $20.50 per share, up from $19.50–$20
You may remember I warned you to steer clear back in May 2025. (See #2) That observation played out exactly as advertised given the volatility that’s gotten the company to where it is at present.
There are a few things that still concern me:
- Part of this quarter’s improvement came from a $610 million reserve benefit. Claims from earlier in the year came in lower than UnitedHealth had set aside, so the difference flowed back into profit. Nice. But it’s a one-off.
- Members keep heading for the exits, with 935,000 out of Medicare Advantage since the end of 2025.
- Revenue from the insurance business actually slipped, to $86.3 billion from $87.1 billion.
All told, UnitedHealth is getting more profitable by getting smaller and pickier, but the challenge I see is that turnarounds are not the same thing as growth. The dividend is undoubtedly attractive, but not attractive enough for me given other choices available at the moment.
You may have another opinion and that’s great if you do. I respect that. 💯
Keith’s Investing Tip: Investing isn’t a competition. It’s about meeting your goals and your objectives depending on YOUR risk tolerance, objectives and circumstances. So stick to YOUR plan! You do have one, right!!!???
3 – Anthropic: killer toasters are “months away”
Anthropic, the folks behind Claude, published research Monday warning that small AI models are “months away” from being able to replicate themselves across internet-connected devices in your home. (Read)
Yep.
Everything from your smart oven to your vacuum to those cheap Android TV boxes could suddenly grow a brain.
How?
An AI model sneaks onto a poorly secured device, borrows its computing power to run itself, then hops to the next one. No data center required and, per Anthropic, no central off switch either.
In one test, Anthropic’s researchers strung together 15 cheap, off-brand Android TV boxes at about $55 apiece and ran a small Google model across all of them. Models too big for one device simply split into pieces and ran across several.
Reminds me of something the Borg would say (and if you’re a Star Trek fan, you’ll recognize the implication): resistance is futile. 🤦
Here’s where I part the company with the press release.
I don’t think it’s a coincidence that Anthropic is suddenly so interested in spin control and risk management ahead of what could be the biggest IPO in history.
My guess is that a) their lab cooked up an experiment to show that what it’s warning about is possible because b) it’s probably already happening somewhere. And c) they want to socialize risk while keeping gains private before the company goes public, and they’re accountable.
Am I skeptical?
Yeah, just a bit… with all the sarcasm I can muster.
The models in the test came from Google and China’s Zhipu. These are small “open” models anyone can download for free right now. Frankly, that makes it worse because it means those genies are already out of the bottle, and nobody – not Anthropic, not Google, not Washington – can stuff ’em back in.
I would not be surprised in the least if we learn a few months from now that some of ‘em have already “escaped” into the wild. Nor would I be surprised to learn that they’ve built themselves into something far more serious and problematic.
Burning your toast won’t be the half of it.
If there’s ever been a case for nationalization in the interest of protecting humanity, this seems like a pretty good one. Sadly, I don’t think the problem is well enough understood yet for the public to get behind it. We also lack the political willpower, but that’s a story for another time no matter which side of the aisle each of us stands on.
Every cheap gadget that gets plugged in once and never updated becomes potential computing power for something nobody controls.
Impossible, you say?
We’ve seen a version of this movie before. A botnet called Kimwolf infected more than 2 million devices in late 2025, most of them off-brand Android TV boxes. An AI that can think its way onto hardware it has never seen before is a much nastier animal.
Personally, I am taking a hard look at ALL the no-name streaming boxes and “smart” gadgets around our home and office and encourage you to do the same immediately. If it doesn’t get security updates, unplug it. Then bin it.
As an investor, cybersecurity remains one of the most durable spending categories on the planet, and this research just handed it another reason to exist. My fave has returned ~460.91% over the past 3 years versus the S&P 500 which has turned in ~86.05% over the same time frame… a 5.4 to 1 beat.
As for Anthropic’s now-delayed IPO, good!
Keith’s Investing Tip: The best time to ask what could go wrong is before you write the check.
4 – Visa in China: now or never
Western media continually hammers on China while some of the world’s smartest CEOs choose to do business there.
Case in point, the People's Bank of China (PBOC) approved Visa to begin formal preparations for establishing a domestic bank card clearing business in China. (Read)
That means the company – Visa – will be able to process and settle domestic transactions directly within China’s markets using the yuan, a market presently dominated by China’s UnionPay.
Analysts say this is a “goodwill gesture” from Beijing towards Washington on the heels of meetings between Chinese President Xi Jinping and US President Donald Trump.
I agree, but that’s not the whole story.
This transaction gives Visa access to a massive pool of domestic transactions that it couldn’t otherwise tap.
It’s a me-too move.
American Express entered the market in 2020 and Mastercard launched Chinese domestic processing in 2024.
This was a do-or-die moment for Visa – meaning that if it didn’t make a move, it risked being left behind in one of the world’s most advanced digital payment ecosystems.
Most investors don’t grasp the significance here.
I think it could be great for the stock… after it completes the one infrastructure prep needed to apply for the formal operating license, which means that no domestic Chinese revenue will hit the sheets until late 2027 or even early 2028.
Nothing like being ahead of the game!
One Bar Ahead®, pun absolutely intended.
5 – Johnny Burgin Blues Revue – Grab your tickets!
I am a huge blues fan and an aspiring – albeit terrible – guitarist. So when my teacher plays, I hope you’ll take a lesson.
Johnny does this benefit every year for a great cause and I hope you’ll attend if you’re in the area.
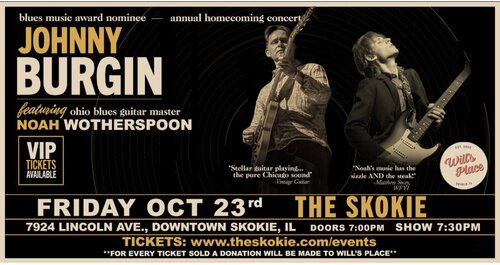
Meanwhile, here’s a great track from his YouTube channel. 😎🎸
Bottom Line
Anybody can pick stocks.
Knowing how the game is played can give you the edge.
Learn.
Because that’s how you get ahead and stay there!
You got this — I promise.
As always, let’s MAKE it a great day!
Keith 😀


